
 by
Learning how to invest in stocks starts with a plan, not a ticker. Define the goal and time horizon, clear the financial risks that can force a bad sale, choose a regulated account, buy a diversified low-cost fund if it fits the plan, automate contributions, and review the allocation on a schedule.
That sounds boring because it is. The difficult work is not finding a secret stock. It is separating money you can leave invested from money you may need, accepting that returns are uncertain, and continuing the contribution when headlines turn ugly. This guide is education, not personalized financial, tax, or legal advice.
Jurisdiction matters: the account limits below are US rules. Indian investors generally need a demat account and a trading or broking account with a SEBI-registered intermediary; SEBI’s securities-trading guide explains the basic route. Readers elsewhere should verify the current account, investor-protection, and tax rules with their own regulator before acting.
Who should not invest in stocks yet
Do not put short-term survival money into a volatile asset. A forced sale during a drawdown can turn temporary market volatility into a permanent personal loss.
- No emergency reserve: FINRA’s emergency-fund guidance says financial planners often recommend three to six months of living expenses in a liquid, interest-bearing account. The right number depends on income stability, dependents, insurance, and access to other cash.
- High-interest debt: paying a 20% credit-card balance creates a certain interest saving; a stock return is uncertain. FINRA uses the same 20% example to show why expensive debt deserves priority.
- Near-term goal: money for rent, tax, tuition, a home deposit, or another fixed expense in the next few years needs a tool matched to that deadline, not a stock allocation chosen for a decades-long average.
- No tolerance for loss: if a 30% account decline would make you sell, reduce the risk before investing. A questionnaire cannot manufacture emotional capacity.
- Product not understood: pause if you cannot explain what the investment owns, how it is priced, what it costs, and how you can lose money.
If you are new to the vocabulary as well as the process, use my guide to the stock market for beginners. The accounting logic behind debt, equity, and capital is also clearer in how businesses manage money and capital.
Choose the account before the investment
The same fund can produce different after-tax results in different accounts. Start with eligibility, withdrawal rules, employer matching, tax treatment, and investor protection. Then compare investments inside the account.
| Account or route | What it solves | 2026 rule or limit | Watch |
|---|---|---|---|
| US taxable brokerage | Flexible investing without an annual contribution cap | No federal contribution limit | Dividends and realized gains can be taxable; protection is not protection from market loss |
| US Traditional or Roth IRA | Retirement account with tax advantages | $7,500 combined IRA limit; $8,600 at age 50+ | Roth eligibility and deductibility use income rules; excess contributions can create tax problems |
| US 401(k) | Payroll contributions and possible employer match | $24,500 employee deferral; $8,000 catch-up at 50+; $11,250 catch-up at ages 60-63 | Plan menu, vesting, fees, and withdrawal rules vary |
| India demat plus trading account | Hold and transact in securities through the regulated market | Use a SEBI-registered intermediary; tax rules are local | Verify registration, charges, nominations, and complaint route |
The IRS IRA contribution-limit page confirms the combined $7,500 IRA limit and the $8,600 limit at age 50 or older. The IRS 401(k) contribution-limit page confirms the $24,500 elective-deferral limit, $8,000 general catch-up, and $11,250 catch-up for participants ages 60 through 63.
In the US, SIPC protection explainer says a qualifying liquidation can cover up to $500,000 per customer, including a $250,000 limit for cash. It does not cover a security losing value, unsuitable advice, or a promise that was never true. Verify that the broker and clearing arrangement are actually covered.
How to invest in stocks: a seven-step process
A beginner needs a repeatable decision process. The seven steps below put risk, regulation, cost, and behavior before a product name.
- 1. Write the goal and deadline. Retirement in 30 years and tuition in three years cannot share the same risk assumption.
- 2. Choose an allocation. The Investor.gov asset-allocation guide explains that time horizon and risk tolerance shape the mix of stocks, bonds, and cash. There is no responsible universal “80% stocks” answer for every beginner.
- 3. Verify the intermediary. Check the broker with the relevant regulator, enable strong MFA, record the recovery route, and understand where assets are custodied.
- 4. Compare the full cost. A $0 trade commission does not eliminate expense ratios, spreads, options or contract fees, currency conversion, advisory charges, account fees, or tax.
- 5. Select the investment. The Investor.gov index-fund guide explains that an index fund seeks to track an index and may have lower costs, but it still carries risk and can lag its benchmark after fees and tracking differences.
- 6. Automate a sustainable amount. Investor.gov definition of dollar-cost averaging means equal portions at regular intervals. It can reduce timing anxiety; it does not guarantee profit or protect against a falling market.
- 7. Define the review rule now. Choose an annual or threshold-based review and write down what would justify a change. A scary headline is not a policy.
What to compare when choosing a broker
Broker selection is a custody-and-operations decision, not a logo contest. Read the current fee schedule, customer agreement, order-routing disclosure, cash-sweep terms, and protection statement.
- Regulation and custody: verify the legal entity you will contract with, not only the brand on the app.
- Trading costs: check commissions plus spreads, contract fees, foreign-market charges, and transfer or closure fees.
- Fund access: a commission-free stock trade does not mean every mutual fund or ETF is free to buy or hold.
- Cash treatment: compare the sweep yield, bank program, insurance limits, settlement timing, and idle-cash defaults.
- Service and recovery: test statements, tax documents, beneficiary settings, MFA, and the path for a locked account.
For US examples, the live pricing pages for Fidelity, Charles Schwab, and Vanguard are useful starting points. They are not a verdict. Read the exclusions and the pricing relevant to the exact account and product you plan to use.
A robo-advisor adds portfolio selection and ongoing management. Compare the advisory fee, underlying-fund cost, cash allocation, tax features, transfer restrictions, and access to a human before assuming automation is cheaper or safer.
Funds vs. individual stocks: the concentration problem
My default for a beginner is a broad, low-cost fund, not a hand-picked basket of companies. Diversification cannot remove market risk, but it reduces the damage one failed company can cause.
- Winner concentration: Bessembinder’s long-run stock study found that the best-performing 4% of US common stocks explained all net stock-market wealth creation from 1926 through 2016; the remaining 96% collectively matched one-month Treasury bills.
- Manager difficulty: the SPIVA U.S. Year-End 2025 scorecard reports that 79% of actively managed US large-cap equity funds underperformed the S&P 500 in 2025.
- Important limit: the 4% result is a lifetime single-stock study, and the 79% result covers one category in one year. Neither proves that every index fund will beat every active fund, or that future returns will match the past.
- Action: if you choose a fund, inspect its index, holdings, concentration, domicile, expense ratio, bid-ask spread, tracking difference, securities-lending policy, and tax treatment.
Speculation deserves a separate risk budget. My notes on the risks of investing in cryptocurrency explain why I would not treat a volatile token as a substitute for a diversified equity plan.
A worked contribution, return, and fee model
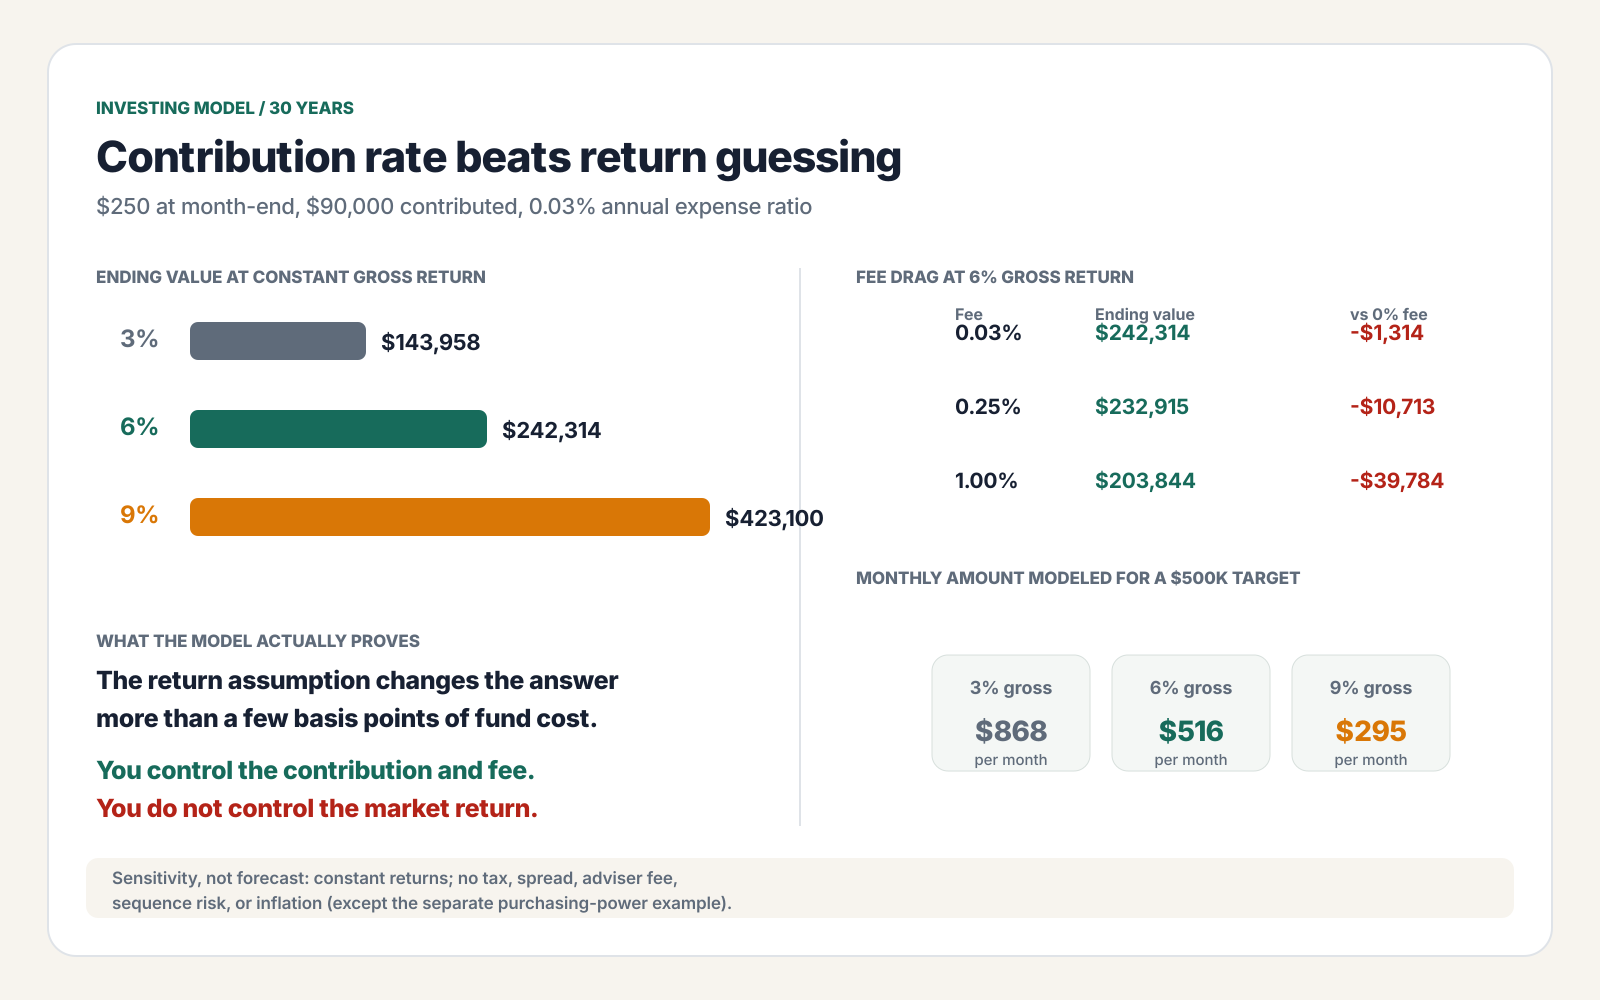
A calculator is useful only when it shows how much the assumption controls the answer. I modeled $250 contributed at the end of each month for 30 years, or $90,000 in total contributions, with a 0.03% annual expense ratio.
| Gross return assumption | Modeled ending value | Monthly amount for $500,000 |
|---|---|---|
| 3% | $143,958 | $868 |
| 6% | $242,314 | $516 |
| 9% | $423,100 | $295 |
- Return sensitivity: the same $90,000 of contributions ends at $143,958, $242,314, or $423,100 under the three constant gross-return assumptions.
- Fee sensitivity: at a constant 6% gross return, a 1% annual fee lowers the modeled ending value by $39,784 relative to a zero-fee case. A 0.25% fee lowers it by $10,713.
- Inflation: $500,000 received 30 years from now has about $205,993 of today’s purchasing power if inflation is a constant 3%. A nominal target and a real target are not the same number.
- Verification: the month-by-month calculation was checked against the ordinary-annuity closed form. The largest difference was below $0.000000001.
This is sensitivity analysis, not a forecast. It assumes constant returns and excludes tax, volatility, sequence risk, spreads, adviser charges, account fees, and behavior. For the mechanics behind growth over time, see the simple math behind long-term growth.
The model’s fee direction is consistent with the SEC investor bulletin on fees: in the SEC’s $100,000, 20-year example at 4% annual growth, the ending values are about $208,000 with a 0.25% annual fee, $198,000 with a 0.50% fee, and $179,000 with a 1.00% fee.
How much should a beginner invest?
Use a repeatable contribution, not a heroic first deposit. There is no universal minimum because brokers, funds, share prices, fractional-share policies, and currencies vary.
- Start with cash flow: subtract essential expenses, required debt payments, near-term goals, and the emergency-fund contribution before choosing an investment amount.
- Capture a genuine employer match: read the plan rules, vesting schedule, investment menu, and fees. “Free money” is incomplete if you ignore those conditions.
- Increase automatically: a small annual or pay-rise step-up is easier to sustain than relying on willpower.
- Keep assumptions conservative: the model shows that a $500,000 goal requires about $868, $516, or $295 per month under 3%, 6%, or 9% gross-return assumptions. You cannot choose which return the market delivers.
Manage the portfolio without managing it to death
Review the plan; do not audition a new strategy every week. A scheduled check can catch allocation drift, rising fees, tax changes, a broken contribution, or a goal that genuinely changed.
- Check contributions: confirm deposits invested as intended instead of sitting in cash.
- Check allocation: compare the current mix with the written target and rebalance through new contributions when practical.
- Check costs: fund expense ratios, advisory fees, and broker schedules can change.
- Check concentration: employer stock, sector funds, and overlapping ETFs can create more single-theme exposure than the account labels suggest.
- Check the goal: a shorter horizon or lower capacity for loss can justify a lower-risk allocation; a market forecast alone does not.
If the weights have moved away from the written plan, use my framework to rebalance your investment portfolio. Consider tax, transaction cost, and account type before selling merely to hit a neat percentage.
Beginner mistakes that are expensive, not exciting
The most damaging mistakes combine concentration, leverage, urgency, and false certainty. If a product needs a countdown timer or a guaranteed-return claim, step back.
- Trading before planning: a watchlist is not a goal, time horizon, or allocation.
- Confusing $0 commission with $0 cost: spreads, fund fees, options charges, tax, and currency conversion still exist.
- Borrowing to invest: margin adds a fixed obligation to an uncertain return and can force liquidation.
- Chasing performance: last year’s winner can be this year’s concentrated risk.
- Trusting unregistered advice: verify the intermediary and never share passwords, OTPs, or remote-device access.
- Ignoring exit mechanics: know settlement, tax, transfer, and withdrawal rules before the money is urgent.
How to invest in stocks: frequently asked questions
How much money do I need to start investing in stocks?
There is no universal minimum. It depends on the broker, fund, share price, and whether fractional shares are available. Start with an amount you can repeat after building emergency savings and controlling high-interest debt. The contribution habit matters more than forcing a large first deposit.
Should a beginner buy individual stocks or an index fund?
A broad, low-cost index fund is the more defensible default because it spreads company-specific risk and reduces the need to identify the rare long-run winners in advance. An index fund still carries market risk, can lose money, and must be checked for its actual index, holdings, expense ratio, tracking, and tax treatment.
Is dollar-cost averaging guaranteed to make money?
No. Dollar-cost averaging means investing equal amounts at regular intervals. It automates behavior and buys more units when prices are lower, but it does not prevent losses or guarantee a profit. A falling investment can keep falling.
Does SIPC protect my investments from stock-market losses?
No. SIPC protection applies when a SIPC-member brokerage fails and customer cash or securities are missing, up to $500,000 including a $250,000 cash limit. It does not insure market value, poor advice, or an investment that declines.
How often should I check or rebalance my portfolio?
Use a calendar or allocation threshold instead of reacting to the news. For example, review once or twice a year and rebalance only when the allocation has moved enough to matter after considering taxes and trading costs. The right threshold depends on the plan, account type, and risk tolerance.
Are the US retirement limits in this guide valid in India?
No. The IRA and 401(k) limits are US federal tax rules. Indian investors generally need a demat account and trading or broking account with a SEBI-registered intermediary, and local tax rules apply. Readers elsewhere should use their regulator and tax authority for account eligibility and limits.
A practical first move
Write one page before opening the account. Put the goal, deadline, emergency-fund status, expensive debt, intended allocation, monthly contribution, fee ceiling, and review date on it. If you cannot fill those fields, you are not ready to select a stock.
Once the page is coherent, verify a regulated account, read the full cost schedule, choose an investment you can explain, and automate an amount you can sustain. The beginner advantage is not a better prediction. It is more time for a disciplined process to work.
Tell Google you want more of this.
Add Gaurav Tiwari as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.